

The Holy Grail of Asset Allocation
Most of us think asset allocation is about maximizing returns.
That's the wrong starting point.
Because if maximizing returns was the only objective, the answer would be simple:
Own as much equity as possible, for as long as possible.
After all, equity investing is ultimately a bet on human progress. Entrepreneurship. Innovation. Human Ingenuity.
Over long periods, few assets have created more wealth.
But that immediately raises an intuitive question:
If equity investing is so powerful, why do so few investors fully benefit from it?
The answer is simple. Because the journey is brutal!
Equity markets do not move upward in a straight line.
They regularly go through:
- 10-20% corrections almost every year
- 30-60% declines every 7-10 years
A deep decline can take years to fully recover from.
And during those years, you are forced to battle something far more dangerous than market declines. Yourself!
This becomes even harder as your wealth grows.
A 50% fall on a ₹10 lakh portfolio is painful. But the same 50% fall on a ₹10 crore portfolio can feel existential.
That is why asset allocation matters.
Not because it maximizes returns. But because it increases the probability that you survive long enough to earn them.
The real purpose of asset allocation is therefore simple:
Reduce temporary declines to a level you can emotionally tolerate, while still retaining enough equity exposure for compounding to work.
That is the balancing act.
And that brings us to the holy grail of investing.
In Search of the Holy Grail
The holy grail for any long-term investor is deceptively simple:
How do we capture most of equity’s long-term return potential while suffering meaningfully smaller temporary declines?
Unfortunately, there is no perfect solution.
Every reduction in temporary declines usually comes at the cost of lower long-term returns.
The objective is therefore not perfection. It is ‘intelligent tradeoffs’.
Here is the framework I use.
Step 1: Decide the Asset Classes
For most investors, the core portfolio only needs three asset classes:
- Equity - the growth engine
- Debt - the stability engine
- Gold - the shock absorber during crisis
Why not Real Estate?
Real estate is difficult to access meaningfully through financial assets today in India. The REIT ecosystem is still nascent, and most investors already have indirect exposure through primary residence, land or family property.
Why not Silver?
Silver is highly volatile and cyclical. It can work tactically, but is difficult to classify as a core asset class.
So for practical portfolio construction, the focus remains on: Equity + Debt + Gold
Step 2: Search for the Sweet Spot
Now comes the important question:
How do we reduce temporary declines without sacrificing too much long-term return?
To answer this, imagine starting with a 100% equity portfolio.
Then gradually reduce equity exposure in two ways:
- First by adding debt
- Then by replacing part of debt with gold (split equally)
We then compare two things:
- Long-term returns
- Temporary declines
This exercise which covers the last 26+ years (Jan 2000 to Apr 2026) leads to three important insights.
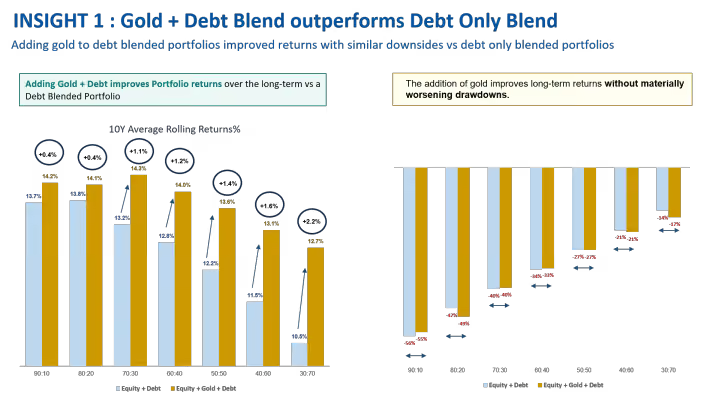
Insight 1: Debt + Gold Blend Works Better Than Debt Only Blend
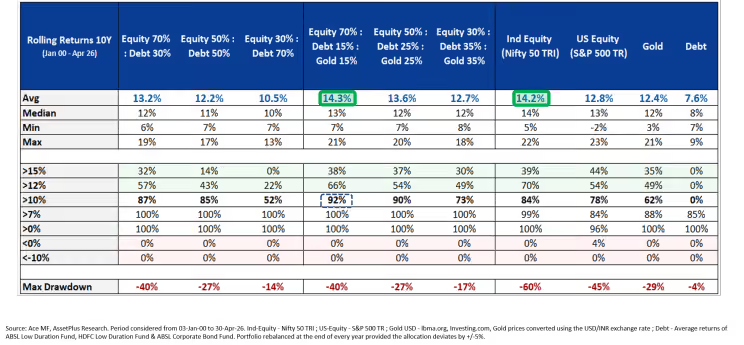
Adding gold to debt blended portfolios improved returns with similar downsides vs debt only blended portfolios.
For example, a 70% Equity:15% Debt: 15% Gold has done better than a 70% Equity: 30% Debt with similar downside.
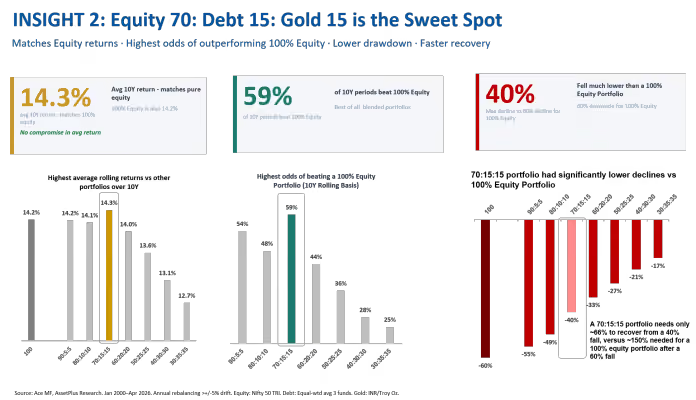
INSIGHT 2: The Sweet Spot -> Equity 70%: Debt 15%: Gold 15%
One allocation repeatedly stands out.
E70% : D15% : G15%
This allocation has historically delivered:
- Returns reasonably close to pure equity
- Meaningfully lower temporary declines
- Better diversification across economic environments
In my view, this is one of the best tradeoffs available for long-term investors.
Just enough equity for compounding to work. Just enough diversification for surviving the bad times.
Insight 3: Lower Equity = Smoother Journey but Lower Returns
Reducing equity further lowers declines, but also reduces long-term compounding.
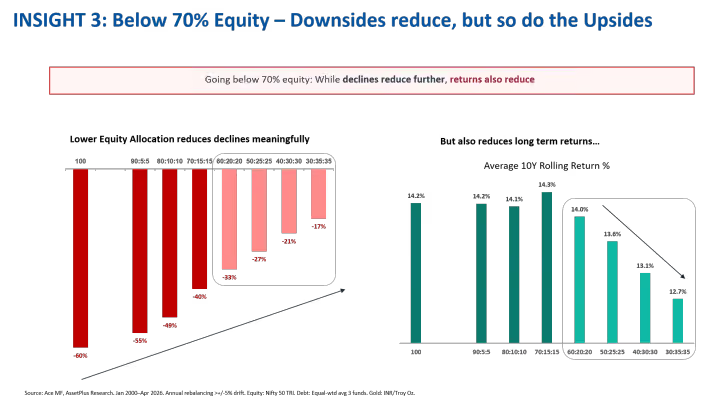
As equity allocation falls:
- Declines reduce
- Emotional comfort improves
But long-term compounding weakens as well.
That is the unavoidable tradeoff in investing.
There is no portfolio that simultaneously:
- Maximizes returns
- Minimizes drawdowns
- Eliminates emotional discomfort
Every portfolio is simply a compromise between the three.
A Simple Framework
Rather than endlessly optimizing allocations by minor increments, I prefer meaningful distinctions.
Three broad portfolios can do the job for most investors.
- Growth : E70 : D15 : G15
- Balanced: E50 : D25 : G25
- Conservative: E30 : D35 : G35
The tradeoff is straightforward:
- Higher equity → higher long-term returns, deeper declines
- Lower equity → smoother journey, lower long-term returns
The right answer depends less on intelligence and more on temperament.
Final Thought
Asset allocation is ultimately a balance between:
- Return maximization
- Decline minimization
- Behavioral survivability
And the last one matters more than most investors realize.
So what’s your asset allocation?